Should You Buy a Calgary Home Now or Wait for Mortgage Rates to Drop?
Is it better to buy a home now or wait until mortgage rates go down?
It depends on what a lower rate would actually save you, because it's usually less than people expect. A one percentage point drop on a $450,000 mortgage saves about $240 a month. If the house you want costs 3% more by the time rates fall, you've given back about a third of that. And right now nobody can promise rates are heading down at all.
The worry underneath the question
Nobody wants to be the person who bought right before rates dropped. I get that. But the fear usually hides a different one, which is "what if I can't keep up with the payment?" That's the real question, and waiting for a rate cut doesn't answer it. A payment you can carry at today's rate is the thing to check first. I had a client who wanted to wait for rates to come down, and by the time rates were low enough for them, the market had corrected, they were in a more competitive buyer's market, and they ended up missing out on the perfect house that was available 6 months earlier.
What a rate move actually does to your payment
Here's an example so you can see the size of it. Say you buy a $500,000 home with 10% down, so a $450,000 mortgage over 25 years. These are illustrations, not a quote, and they leave out your mortgage insurance premium, property tax and heat.
- At about 4.4% (roughly today's best insured five-year fixed): about $2,476 a month
- If rates fell one full point to about 3.4%: about $2,232, which saves roughly $245 a month
- If rates rose half a point to about 4.9%: about $2,602, which costs roughly $125 more
Now the other side of the scale. If that same home goes up 3% while you wait, the mortgage rises by about $15,000 and your payment goes up roughly $75 a month at today's rate. Waiting for a half-point cut might get you back to even. Waiting for a half-point cut and then competing with every other buyer who was also waiting probably doesn't.
What I'd watch more than the rate
The rate is one number. The price you pay and the terms you negotiate are two more, and right now those are the ones you actually control. A buyer who gets a few thousand dollars off, a possession date that suits them, and solid conditions has done more for their monthly cost than most rate drops would.
Where things stand right now (as of November 3, 2026)
- The Bank of Canada raised its rate to 2.5% on October 28, its first increase since 2023. Inflation hit 3.1% in September, mostly from energy. The next decision is December 9.
- Markets are pricing in more hikes, not cuts. A Reuters poll in late October had 16 of 29 economists expecting another hike by March 2027. That's what the market expects, not a promise.
- Fixed rates follow bond yields, not the Bank's rate directly. The lowest insured five-year fixed on Ratehub today is about 4.44%.
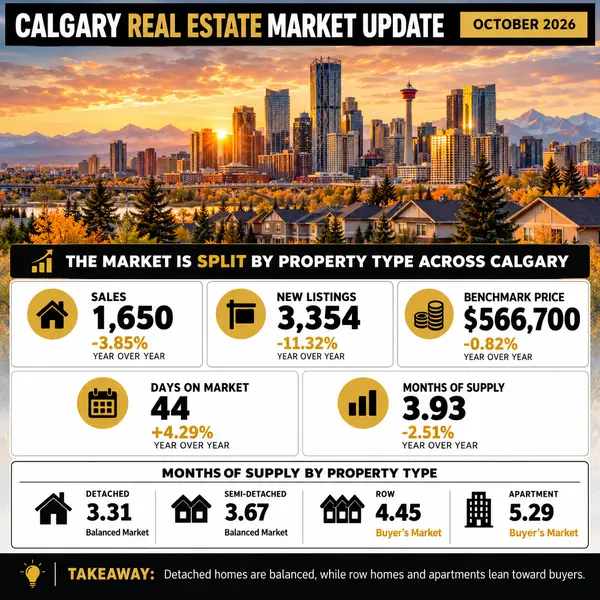
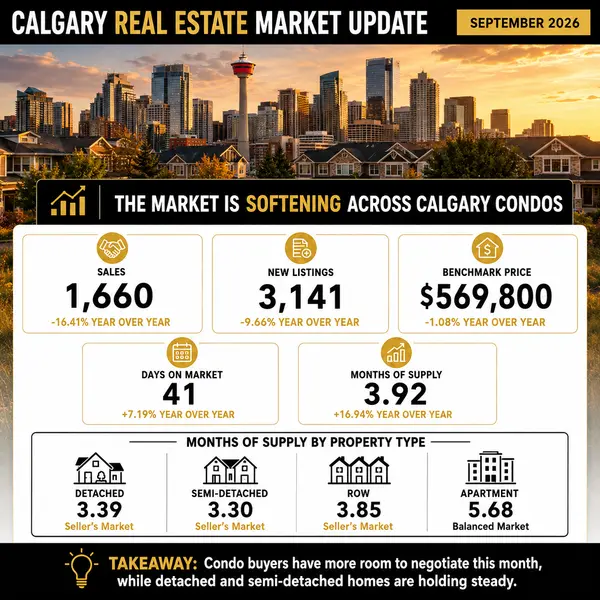
- CREB's October release has Calgary sales at 1,592, down 15.3% from a year ago, and inventory at 6,173, down 4.6%. The citywide benchmark price is $564,200, and months of supply is just under 4. Detached is $735,100, semi-detached $685,200, row $407,500 and apartment $288,800. Row is down about 5% and apartment is down about 8% from last year, while detached and semi-detached are holding.
Put plainly, sales are slow, months of supply is just under 4, and row homes and condos are cheaper than they were a year ago. That gives a buyer some room to negotiate. If rates did drop, more buyers would likely come back, and that room could shrink.
What I'd do
I wouldn't build a plan around a rate forecast. The Bank held at 2.25% for about a year and then raised, so I wouldn't trust anyone who says they know the next move. I'd do two things instead.
First, run your payment at today's rate, then run it again at a rate a full point higher. If you can carry both without losing sleep, buy when you find the right home. If it only works at a lower rate than you can get today, the answer isn't to wait for a cut. It's to save more, look at a smaller or older home, or talk to a mortgage broker about other options before you start looking.
Second, use the slower market. Ask for conditions, a fair price and a timeline that works for you. You can't negotiate a better rate with the seller, but you can negotiate the price, and that lasts for as long as you own the place.
If rates do fall later, you can usually renew or refinance into a lower one. Just ask your lender about the penalty before you sign. You can't undo a price you paid too much for. If you are nervous and wonder whether to wait, let the numbers make the decision for you. Hoping for a rate move to make the math work is not a strategy.
I also wrote about the mortgage basics in Understanding Mortgages: What Calgary Buyers Need to Know, and the market snapshot in Calgary market overview: October 2026.
Common questions
Will mortgage rates go down in Calgary soon?
Nobody knows. The Bank of Canada just raised its rate to 2.5% and markets are pricing in more hikes. Fixed rates follow bond yields. Plan around a payment you can carry today.
Should I wait for rates to fall before buying a house?
It depends. A one point drop saves about $240 a month on a $450,000 mortgage, but prices can rise if buyers return. Run your payment at today's rate and one point higher.
Can I refinance if rates drop after I buy?
Usually, yes, at renewal or by breaking the term. Ask your lender what the penalty would be before you sign.
Is it a good time to buy in Calgary right now?
Sales are down about 15% from a year ago and row and condo prices are lower, so buyers have some room to negotiate. It still depends on your payment and the home itself.
Where this leaves you
If you're not sure whether your numbers hold up at today's rate, bring them over and we'll go through them together before you tour anything.
This post is general education, not mortgage, financial or legal advice. Rates and market figures change often. Check your own situation with a mortgage professional. Example numbers are illustrations, not a quote.
Recent Posts